Analysis & Commentary
Look beyond the headline. Understand the system beneath it.
Read our research analysis and commentary on the economic, technological and commercial forces shaping markets, industries and global trade.
Identify what changed in the available evidence.
Examine the system and incentives behind the change.
Consider why it matters and what remains uncertain.
Current questions
Eleven stories. Eleven deeper questions.
Each section pairs a focused answer with visual evidence and a clear interpretation. Choose the brief for a concise overview or open the full research note for the complete argument, charts and references.
11 Technology & Markets
What would it take for the $800 billion AI spending bet to pay off?
Answer in brief
Five companies expect to spend more than $800 billion on capital projects in 2026, much of it driven by AI. The investment depends on AI revenue growing fast enough to cover the cost of building and running that capacity within the chips’ working life.
The research note models a five-year chip life in its base case. The spending estimate includes capital projects beyond AI.
10 Shipping & Energy
Why can oil stay expensive after the Strait of Hormuz reopens?
Answer in brief
Before the war, about a fifth of the world’s oil passed through the strait. The closure disrupted shipments almost overnight. Oil started moving again, but the research found that moving it out of the Gulf still cost more than before the closure.
The research note follows Gulf oil shipments before, during and after the closure in 2026.
Commentary
Restoring shipments and restoring their previous cost are two different steps.
The strait’s importance comes from the volume of oil concentrated in one passage. Reopening allows traffic to resume. Buyers still feel the disruption if the cost of getting those barrels to market remains elevated.
What matters: Track the cost of moving oil out of the Gulf alongside the volume of shipments.
09 Commodities & Global Trade
Why don’t plastic prices always move with oil and gas?
Answer in brief
Oil and gas are inputs to plastic, but resin prices also reflect how much material producers can supply and where buyers can source it. The 2026 US price moves described in the research show that resin can rise faster than its feedstocks or hold steady as oil rises.
The research note compares US resin and feedstock price moves and traces how years of capacity expansion in China shaped supply.
Commentary
Production capacity can change how much of a cost increase reaches the buyer.
Feedstock prices set part of the cost of producing resin. Available production capacity and competition determine how much of that cost suppliers can pass through. That is why the same move in oil can produce different outcomes for resin.
What matters: Compare resin prices with feedstock costs and available supply before attributing a change to crude oil.
08 Currencies & Macroeconomics
If the dollar’s reserve share is falling, what is replacing it?
Answer in brief
The research finds that the dollar’s share of official reserves has declined over roughly twenty-five years. Central banks have spread holdings across alternatives, but no single currency, commodity or digital asset has taken the dollar’s place.
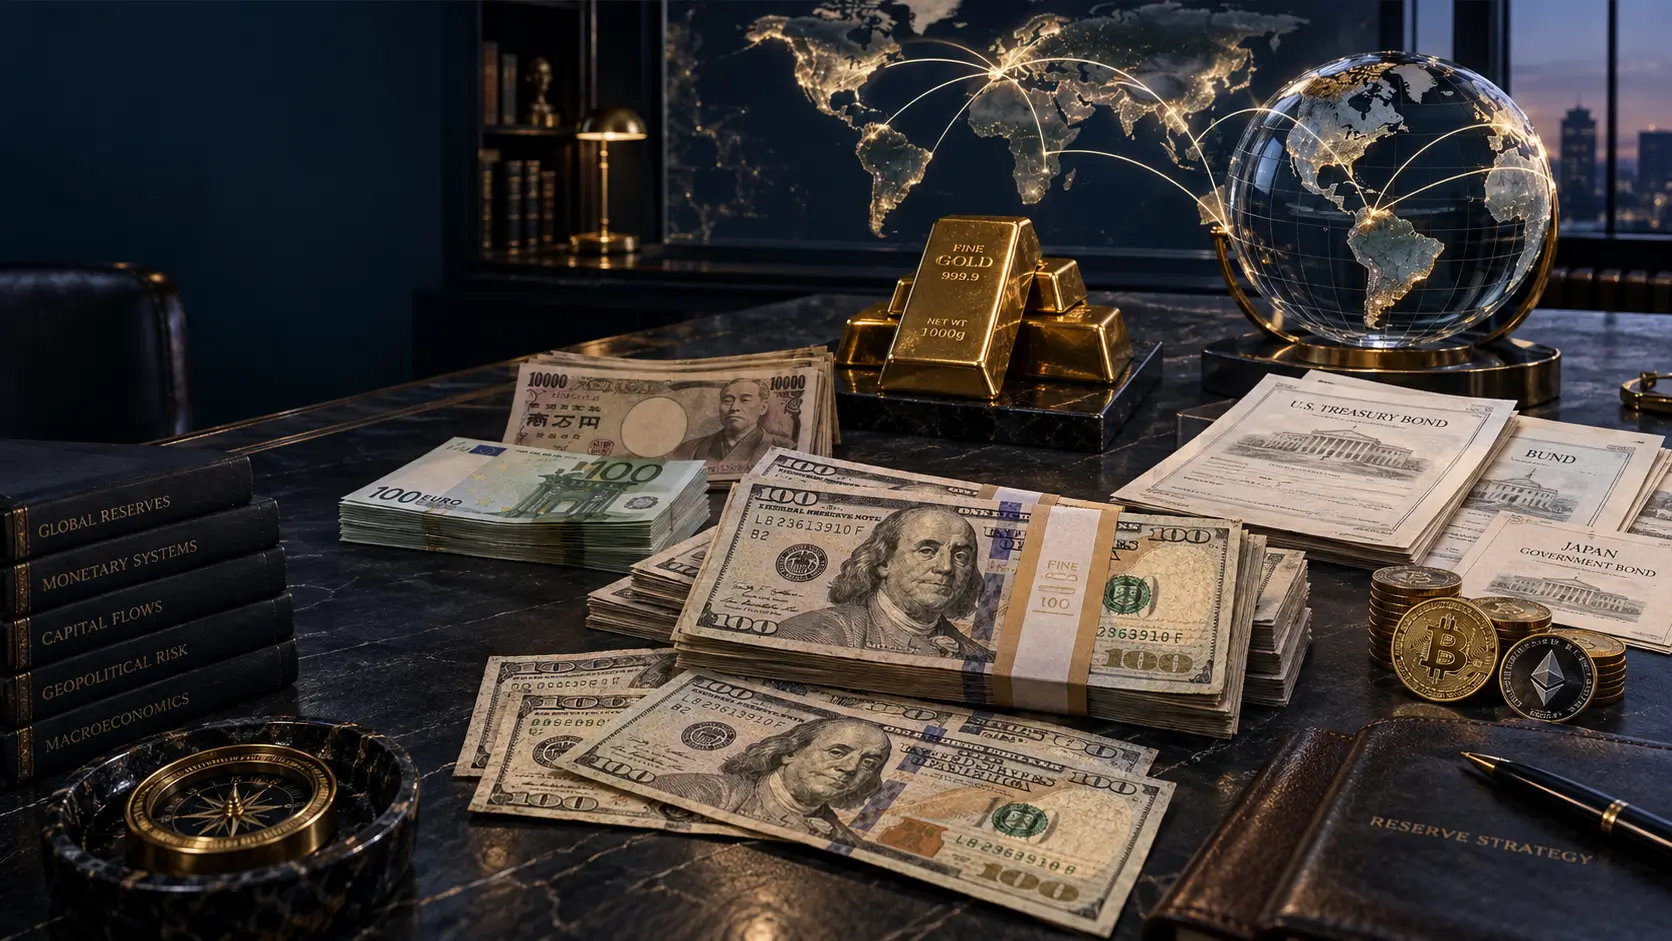
The research note examines changes in reserve composition and the limits of the alternatives.
Commentary
Reserve diversification can coexist with continued dollar dominance.
A central bank can hold fewer dollars without choosing a new dominant currency. Several alternatives can each absorb a portion of the shift, leaving the dollar with a smaller share even as it remains the leading reserve currency.
What matters: Look at where reserves are going as well as how much of the total the dollar has lost.
07 Currencies & Macroeconomics
Why can gold rise during both inflation scares and recession fears?
Answer in brief
Both conditions can reduce the real return available from safe bonds. Inflation raises expected price growth, while recession fears increase the likelihood of interest-rate cuts. Either path can lower real rates and reduce the opportunity cost of holding gold.
Conceptual mechanism based on the complete research note; it does not imply a fixed price relationship.
Commentary
Gold is better understood through opportunity cost and monetary trust than through a simple inflation story.
Falling real rates make non-yielding gold more competitive with government bonds. At the same time, central-bank diversification creates a separate source of demand for an asset that has no issuer, counterparty or foreign government able to freeze it.
What matters: investor demand and sovereign reserve demand follow related but distinct logic, so gold’s rally cannot be explained by inflation alone.
06 Technology & Artificial Intelligence
Why can only three companies build the world’s most advanced chips?
Answer in brief
Leading-edge chipmaking combines exceptional capital intensity, specialised equipment, decades of process knowledge and the ability to achieve reliable yields at enormous scale. Buying a fabrication plant or a lithography machine cannot reproduce that complete industrial system by itself.
Conceptual mechanism based on the complete research note; no market-share values are implied.
Commentary
The real bottleneck is not one factory. It is an accumulated system that very few firms can reproduce.
Advanced semiconductors depend on a narrow chain of capabilities: EUV lithography equipment, foundry process expertise, specialised suppliers and the continuous learning required to improve yields. AI demand makes each constrained link more economically and strategically important.
What matters: concentration turns an industrial advantage into systemic risk because disruption at one irreplaceable node can affect technology markets worldwide.
01 Currencies & Macroeconomics
Why can the yen weaken while Japan remains a major creditor?
Answer in brief
Creditor status and currency demand are not the same thing. Japan can own substantial assets abroad while much of that portfolio remains denominated in dollars rather than yen.
Approximate split highlighted in the full note. The non-yen share includes 56% denominated in U.S. dollars.
Commentary
External wealth does not automatically translate into yen strength.
The currency mix helps explain why a large overseas asset position can coexist with a weak exchange rate. Funding, investment and hedging decisions still shape the demand for yen.
What matters: the composition of capital is as important as its total size.
02 Currencies & Macroeconomics
How much can a burger really tell us about a currency?
Answer in brief
The Big Mac Index offers an accessible purchasing-power signal, but it is not a complete valuation model. Local wages, rents, taxes and distribution costs also influence the price.
Raw Big Mac Index reading, January 2025.
Commentary
A clear signal is useful, but it is still only one signal.
A large gap raises a worthwhile question about purchasing power. It does not, by itself, identify the exchange rate that should prevail or predict when the market will move.
What matters: use the index to begin the analysis, not to end it.
03 Energy & Infrastructure
When does cheap electricity hide an expensive system?
Answer in brief
A low retail tariff does not show the full cost of generation, network maintenance and new investment. Affordability and system sustainability have to be examined together.
Growth multiple; not a tariff comparison.
Commentary
The bill paid by a consumer is only one part of the system.
Revenue growth can improve financial capacity, but the wider question remains whether pricing, investment and service quality are moving together over time.
What matters: low prices are durable only when the system delivering them can keep operating and investing.
04 Commodities & Global Trade
Who captures the value in a cup of coffee?
Answer in brief
The retail price is created across farming, processing, logistics, branding and service. The share associated with the producing country is therefore very different from the final amount paid for the drink.
Commodity coffee producer-country share, 2015–2019, as discussed in the full research note.
Commentary
The farm-gate price and the café price describe different stages.
Labour, processing, climate exposure, freight and consumer-facing costs all shape the final price. The chart is a value-chain view; it should not be read as the farmer’s individual income share.
What matters: price differences become clearer when each stage of the chain is examined separately.
05 Infrastructure & Global Trade
How much of an airport business exists beyond the runway?
Answer in brief
Flights create the passenger and cargo flows, but modern airport economics extends well beyond landing charges. Parking, ground transport, rental cars, retail, food, property and other commercial activity can form a substantial part of the revenue base.
U.S. airport revenue mix highlighted in the complete article; FY2023.
Commentary
The runway creates the flow; the commercial system determines how much of that flow is monetised.
The 54–46 split shows why an airport should not be analysed only as transport infrastructure. Commercial revenue is closely tied to passenger access, dwell time, terminal design and the use of airport land. Aviation remains the traffic engine, while the surrounding commercial layer changes the economics of the asset.
What matters: airport value depends not only on how many people or tonnes move through the system, but on how the operator converts those flows into durable revenue.
Editorial principle
Evidence sets the boundary. Commentary explains the consequence.
We make the reasoning visible, distinguish an observed fact from an interpretation, and state uncertainty where the available information does not support a stronger conclusion.
Continue reading
Follow the complete argument.
Visit Latest Articles to explore all eleven articles, then choose the brief or the full research note that suits the time you have.
Commentary
The timing of revenue matters as much as its eventual size.
Demand can keep growing while returns fall short. If new capacity earns too little in its early years, the owners have less time to recover their investment before they need to replace the hardware.
What matters: Watch how quickly revenue from AI services grows against the cost of the infrastructure built to deliver them.